Credit decisions
Can this customer have credit? Decide it the same way, every time.
Turn your customer credit approval rules into one decision your CRM and ERP can call. New accounts, limit increases and credit holds are handled consistently, and every answer comes with its reason.
Incoming request
evaluatingCan Harbour Trade Ltd have a £20,000 limit?
- Look up the maximum starting limit for the customer's years trading in the Credit bands lookup table
- If the customer's country is on the Restricted countries list, decline
- If the requested limit is within the band, approve it automatically
- If the requested limit is above the band, refer it to the credit controller
Answer, with the reason
Refer to the credit controller. Six years' trading puts Harbour Trade in a band with a £15,000 starting limit, so the £20,000 request is above the band. The trace shows the band that was found, and the controller can decide on the extra £5,000 with the facts in front of her.
Sound familiar?
Credit calls that depend on who you ask
Sales wants a yes today. Credit control wants to be sure. The rules sit somewhere in between.
"Sales has promised them 60 days"
A new customer is ready to order, but nobody can confirm terms until the credit controller has looked at it. The deal cools while it waits.
"Why did they get £20k when we got £10k?"
Two similar customers get very different limits because different people handled them. Neither decision was wrong on its own; they were just inconsistent.
"The order went out while they were on hold"
The credit hold was noted in one system, but the order came in through another. The goods shipped to a customer who was already over their limit.
The quiet cost
What inconsistent credit decisions cost
- Good customers wait days for an answer and take their order elsewhere.
- Limits set on gut feel expose the business to debts it did not plan for.
- Orders ship to accounts that should have been on credit hold.
- Credit control spends its time on routine requests instead of the risky ones.
Before and after
From case-by-case calls to one clear credit policy
Today
- Every credit request queues for a person to review
- Limits vary depending on who handled the account
- Credit holds applied in one system and missed in another
- No clear reason on record for a limit or a hold
With Condexa
- Routine requests answered in milliseconds; exceptions go to credit control
- The same rules applied to every customer
- Every system asks the same decision before an order is accepted
- A trace behind every limit, hold and referral
How you get there
How credit decisions become consistent
- 1
Your credit policy, in black and white
Lay out the checks your credit team already uses: trading history, requested limit, overdue invoices and restricted countries. Bands and limits live in lookup tables they own.
- 2
Proof it matches your judgement
Run past applications through the decision and compare the answers with what credit control actually decided. The trace makes any gap obvious.
- 3
Credit answers wherever the order starts
Your CRM, ERP or customer portal asks the same decision before accepting a new account or an order. Credit control only sees the cases that genuinely need them.
A worked example
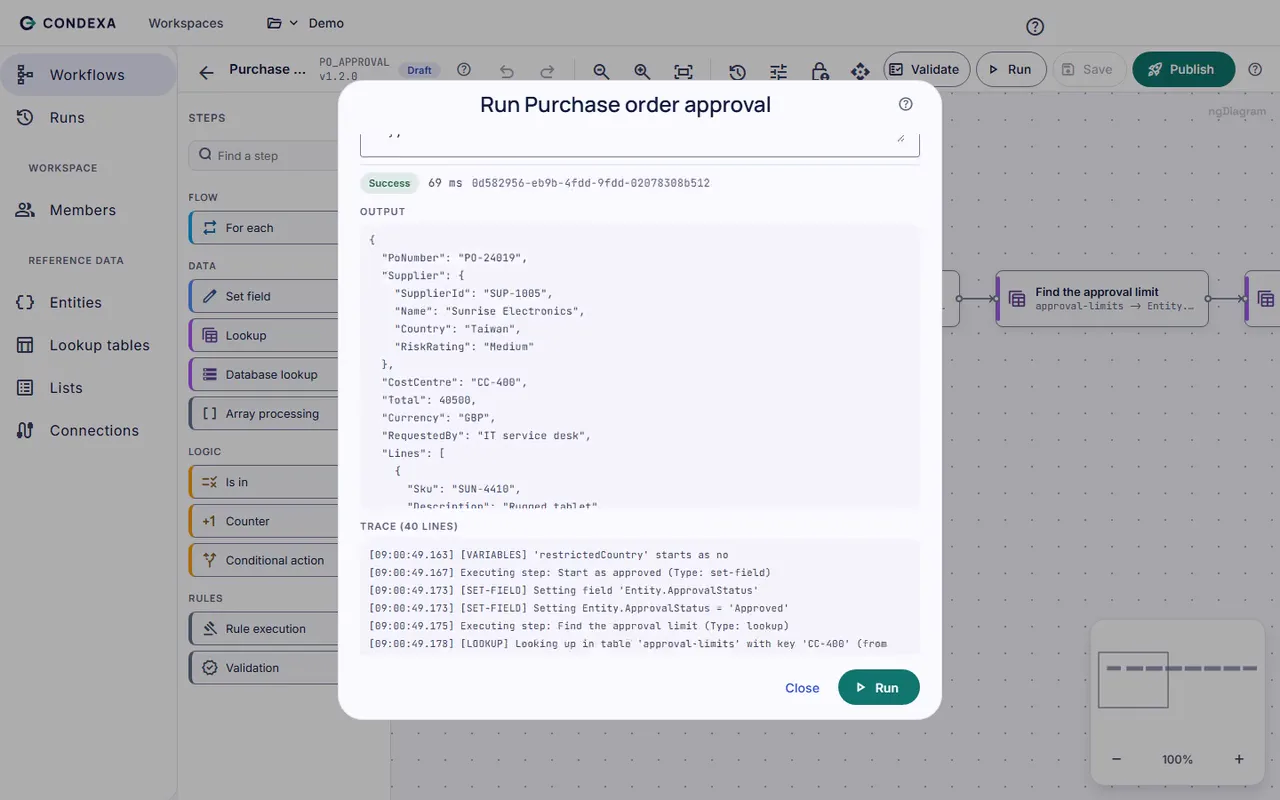
Example: a new trade account asks for £20,000
Harbour Trade Ltd, trading for six years, applies for a £20,000 credit limit on 30-day terms. The sales rep has entered the application in the CRM.
The rules, in plain English
- R1Look up the maximum starting limit for the customer's years trading in the Credit bands lookup table
- R2If the customer's country is on the Restricted countries list, decline
- R3If the requested limit is within the band, approve it automatically
- R4If the requested limit is above the band, refer it to the credit controller
Condexa answers
Refer to the credit controller. Six years' trading puts Harbour Trade in a band with a £15,000 starting limit, so the £20,000 request is above the band. The trace shows the band that was found, and the controller can decide on the extra £5,000 with the facts in front of her.
FAQ
Questions people ask
What are customer credit approval rules?
Customer credit approval rules decide whether a customer can buy on account, what limit they get and what terms apply. They usually weigh up trading history, the amount requested, payment behaviour and any restrictions. Writing them down as a decision means every customer is judged the same way.
What is a typical credit limit approval process?
A customer or sales rep requests a limit, credit control checks it against policy, and the limit is either approved, reduced or referred to someone more senior. Automating the routine part means small, straightforward requests are answered at once and only the exceptions reach a person.
Is Condexa credit decisioning software?
Condexa is a decision automation platform that you can use for credit decisions. You write your own credit rules, and your CRM or ERP calls them for an answer. It does not supply credit scores itself, but it can use data you already hold in SQL Server or Dataverse.
Can it put an order on credit hold automatically?
Yes, if that is your rule. The decision can check the order value against the customer's limit and any overdue invoices, and return a credit hold result. Your ERP then acts on the answer, and the reason is recorded in the run history.
How do we explain a credit decision to a customer?
Open the run in the history and read the trace. It shows the data the decision used and the rule that led to the result, so you can tell the customer exactly what applied and what would change the answer.
Keep exploring
Related decisions and guides
Problems
Unexplained decisions
Can you explain why the system declined that order? Keep a step-by-step record behind every automated answer.
Read moreProblems
Spreadsheet decision logic
Your approval matrix lives in Excel, one file has three versions, and no system can ask it anything.
Read moreIndustries
Wholesale and trade
Every branch and rep prices a little differently. Apply trade credit and discount limits the same way, everywhere.
Read moreFeatures
Decision trace
Someone asks why the system said no. Open the run and show them every step, every value and the rule that decided.
Read moreIntegrations
SQL Server
Business rules buried in stored procedures? Keep your data in SQL Server and move the rules somewhere people can read.
Read moreSee your credit policy answer a real application
Bring a decision your team makes every week. We will build it with you, live, test it against your own examples and show your systems calling it.
No slides. Your decision, built live. No obligation.